— Retirement & Investment Planning —

You only make this passage once. Know your harbor.

Retirement is the close-quarters part of the trip. Income, taxes, timing, and no room left to drift. KBR is an independent, fee-only advisory practice in Londonderry, New Hampshire, working across the state line into Massachusetts. Bernie Ross has been running this stretch of water since 1997.

1997 In financial services since
Fiduciary Advice given in a fiduciary capacity
Fee-Only Paid by clients, never by product sponsors
03053 Londonderry, New Hampshire

What does KBR do?

KBR Financial Solutions is an independent, fee-only registered investment advisory practice in Londonderry, New Hampshire, working with pre-retirees and retirees across southern New Hampshire and neighboring Massachusetts. Retirement income planning, investment management, Social Security timing, rollovers, estate coordination and long-term care planning are handled in one place, by one advisor, for one household at a time. As a fee-only registered investment adviser, KBR is held to a fiduciary standard at all times.

— Who this practice is for —

Two passages, one chart.

The work looks different depending on where you are in the crossing. Most people arrive here in one of two places.

Still under way

Five to fifteen years out

You have been saving into a 401(k) for decades and the balance looks fine on paper. What you do not have is a year-by-year picture of what that balance actually pays you, after tax, for thirty years.

  • Turning accumulated savings into a written income schedule
  • Deciding what happens to the 401(k) when you leave the employer
  • Modeling Social Security at 62, at full retirement age, and at 70
  • Finding the tax work that has to happen before you stop earning
Already in port

Drawing income now

The paycheck has stopped and the portfolio has to replace it. The question is no longer what the account returned last year. It is which account you spend from next, and what that decision costs in tax and in flexibility later.

  • Withdrawal sequencing across taxable, tax-deferred and Roth accounts
  • Required minimum distributions and the tax brackets they push you into
  • Planning for long-term care before it is an emergency
  • Making sure the plan holds if one spouse is suddenly managing it alone
— Late-Stage College Planning —

Tuition and retirement are the same money.

The four years you spend paying for college sit directly on top of the years you are supposed to be finishing your retirement savings. Handled separately, they compete. Handled together, they can be sequenced.

"We earn too much to qualify for financial aid."

That is the most common assumption families bring to this conversation, and it is worth testing rather than accepting. Aid eligibility is calculated from a formula, not from an income cutoff. The formula weighs how assets are titled, which parent owns what, how many children are enrolled at once, and how each school chooses to read the numbers. Two households with the same income can land in very different places.

Late-stage college planning is the work done once your student is already in high school, when the accounts are what they are and the remaining moves are positioning, timing and school selection.

  • Reviewing how the current aid formula reads your household, including the Student Aid Index that replaced the EFC
  • Positioning assets and income in the years the forms actually look at
  • Comparing what different schools are likely to offer the same family
  • Deciding what gets funded from savings, cash flow, or borrowing, and what that costs the retirement plan
  • Coordinating the whole thing with the income plan rather than beside it
— How the work runs —

The passage plan.

Four steps, in order. Nothing gets recommended until the first two are finished.

01 / Soundings

Take the depth

Tax returns, Social Security statements, pension and annuity contracts, estate documents and current holdings. The whole picture before any advice.

02 / Chart

Plot the course

A written plan showing the income schedule, the tax path, the claiming decision and what the portfolio has to do to support it.

03 / Under way

Put it in motion

Accounts opened and funded, rollovers processed, allocations set, beneficiaries confirmed and documents coordinated with your attorney and CPA.

04 / Correct

Adjust for drift

Scheduled reviews against the plan, not against the market. Tax law changes, health changes and family changes all move the line.

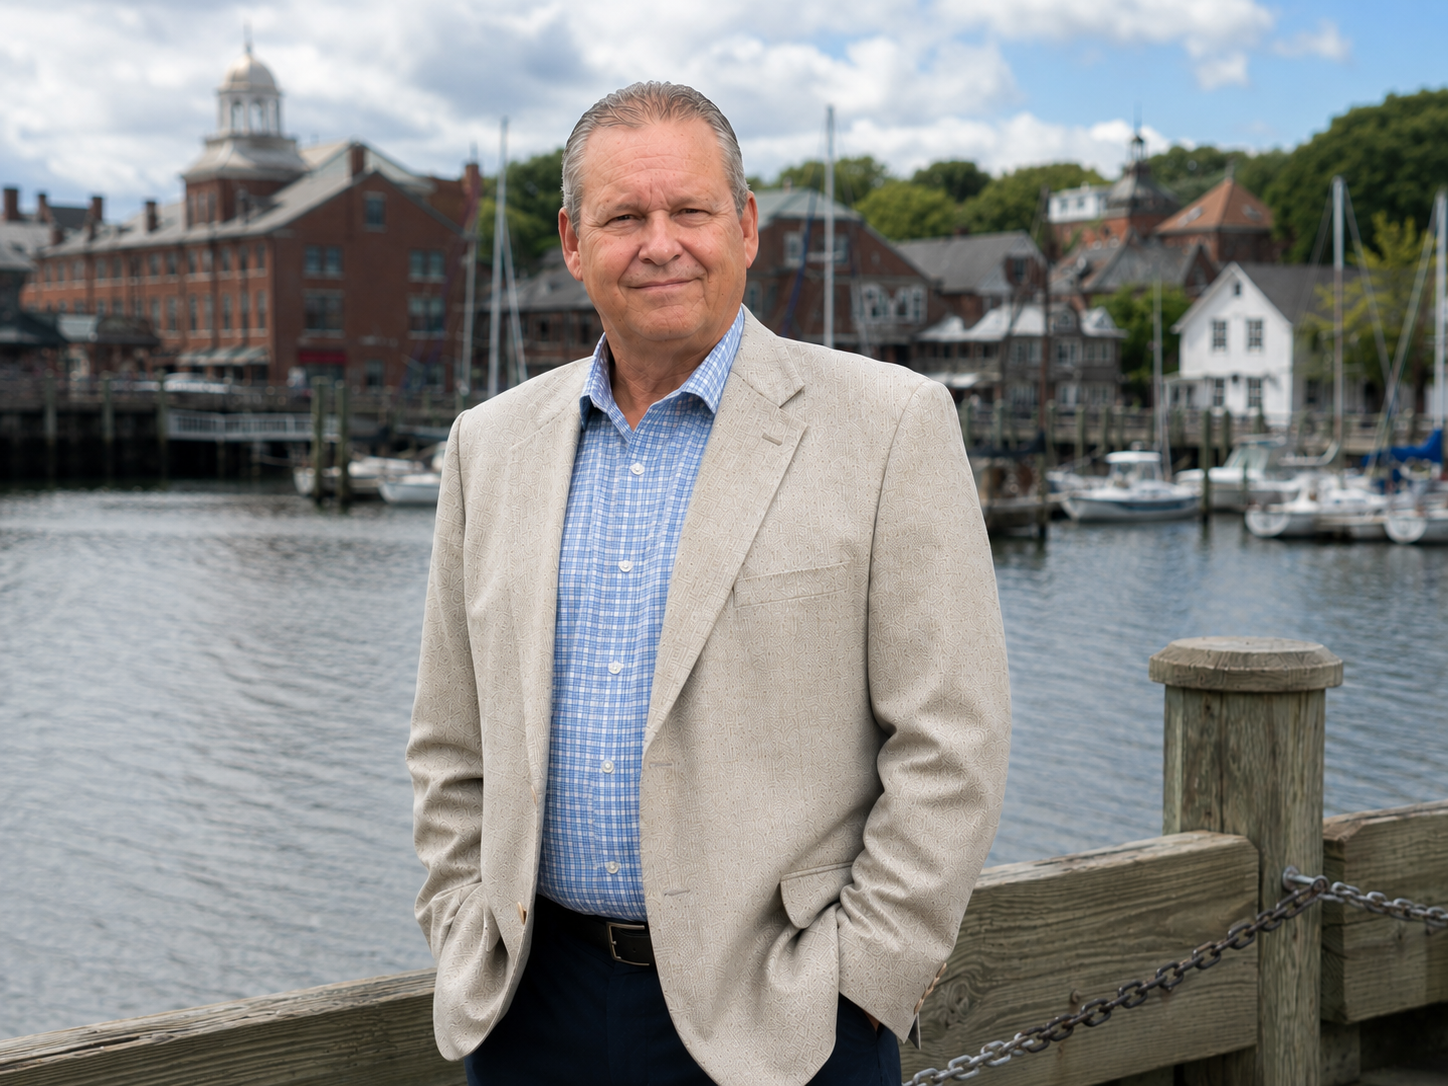
Bernie Ross of KBR on a New England harbor waterfront
— Who you will be working with —

One advisor. The same one, in year ten.

Bernie Ross entered financial services in 1997 and has served clients across New Hampshire and Massachusetts ever since. He holds the Series 65 license and a B.A. in Economics from the University of Massachusetts Amherst.

Fee-only means he is paid by his clients and by nobody else. He is not employed by a brokerage, a fund company or an insurance carrier, there is no home office recommending a product list, and no product sponsor pays him anything. It also means the person who builds your plan is the person who answers the phone about it four years later.

Most of his clients live within about sixty minutes of the office, on both sides of the state line. A number of them he has worked with since before they retired, which is the only way to know whether a retirement plan actually held.

Read Bernie's full background

— Where clients are —

Southern New Hampshire and neighboring Massachusetts, mostly within an hour of the office.

The office sits at 1B Commons Drive in Londonderry, off Exit 4 on Route 93, between Manchester and the Massachusetts line. Meetings happen in person or by video, whichever suits you.

LondonderryDerryEast DerryWindham SalemManchesterBedfordNashua HudsonMerrimackAuburnChester

See every community we serve

— Common questions —

Before you pick anyone, ask these.

What should I look for when choosing a retirement financial advisor in Londonderry NH or southern New Hampshire?

Look for four things you can verify. First, how the advisor is registered and whether investment advice is given in a fiduciary capacity, which you can check on the SEC and FINRA public disclosure sites. Second, how the advisor is paid, including advisory fees, commissions, or both. Third, whether the work covers your whole picture (income, taxes, Social Security, estate, insurance) or only the investment account. Fourth, who you will actually be talking to in year five, because at larger firms the person who sells you the relationship is often not the person who services it.

Is KBR fee-only, and why does that matter?

Yes. Fee-only means the only compensation the firm receives comes from its clients. No commissions, no trailing commissions, no revenue sharing and no payments of any kind from product sponsors. It matters because it removes the financial reason to prefer one recommendation over another. A fee-based advisor, by contrast, charges client fees and may also earn commissions on the products they recommend. The fee schedule is set out in the KBR brochure, linked in the disclosures at the bottom of every page.

What does a comprehensive retirement plan actually include?

A comprehensive retirement plan sets out where your income will come from each year and in what order accounts are drawn down. It covers Social Security timing, required minimum distributions, the tax treatment of each account, how the portfolio is invested against the income schedule, what happens if one spouse dies or needs long-term care, and how assets pass to heirs. A plan that only allocates an investment account is a portfolio, not a retirement plan.

How do I know whether an advisor is looking at my whole financial picture instead of selling products?

Ask what the advisor needs to see before making a recommendation. An advisor working from the whole picture asks for tax returns, Social Security statements, pension and annuity contracts, estate documents, and existing insurance before recommending anything. An advisor working from a product asks about the balance of the account being moved. Ask for the recommendation in writing with the reasoning attached, and ask what the advisor is paid in each scenario.

What questions should I ask a retirement planner before hiring them?

Ask how they are registered and in which states. Ask for their brochure and their CRD number. Ask exactly how they are paid and whether they receive commissions. Ask who holds the assets and confirm it is an independent third-party custodian, not the advisor. Ask how often you will meet and what happens between meetings. Ask what a client of theirs looks like, and whether that resembles your situation.

Start with the chart, not the boat.

The first meeting costs nothing and commits you to nothing. Bring your last tax return and your Social Security statement, and you will leave knowing more than you came in with.